Daniel Rivera Alves
Founding Partner, Elit Capital
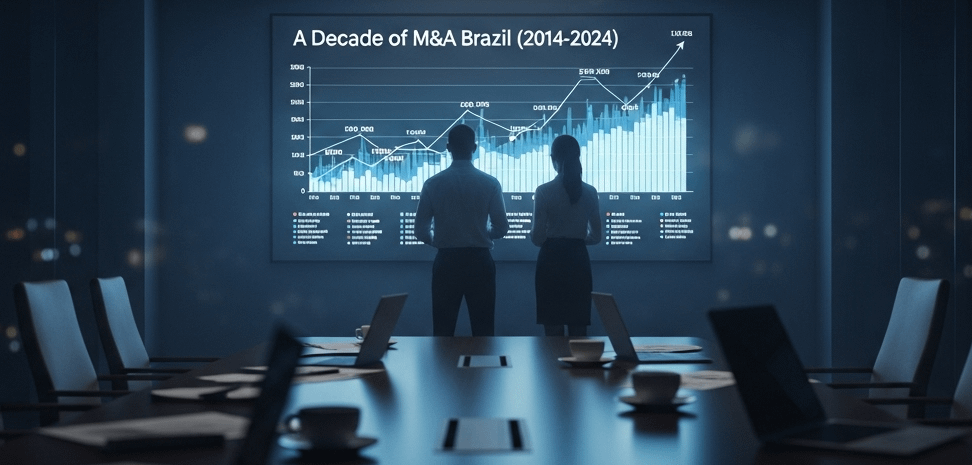
The Brazilian M&A market went through a full cycle over the past decade: a slowdown in the mid-2010s, a recovery from 2017 onwards, a record number of transactions in 2021 and normalization over the following two years, with a partial rebound in value in 2024.
According to TTR Data, volume went from around 1,000 transactions a year between 2014 and 2019 to a record in 2021 (2,560 deals), fell back in 2022 (2,119) and held a similar level in 2023 (2,123), before dropping to 1,674 in 2024. In value, the aggregate followed the same curve, peaking in 2021 (~R$ 476 billion), cooling in 2022 (~R$ 325 billion), falling again in 2023 (~R$ 217 billion) and recovering in 2024 (~R$ 260 billion), always considering only transactions with disclosed values.
The sector evolution of M&A in Brazil between 2014 and 2024 shows digitalization as the main driver of deals. Technology — encompassing internet, software and IT services — went from a supporting role to the lead between 2020 and 2022, driven by e-commerce, payments, SaaS, data solutions and Artificial Intelligence (AI).
Healthcare grew steadily, with hospital consolidation and the expansion of laboratories, health insurers and healthtechs. Energy and Infrastructure alternated peaks linked to privatizations, concessions and portfolio reorganizations, gaining ground in 2023 and 2024 as interest in defensive assets increased.
Financial Services also stood out, bringing together banks, brokerages, payment companies and fintechs, combining traditional consolidation with technological disruption. Real Estate & Construction remained active in transactions involving developers, shopping malls, logistics assets and commercial projects, following credit and investment cycles. Retail & Consumer Goods — from store chains to food, beverages and fashion — remained relevant, reflecting expansion, repositioning and portfolio diversification.
Strategic buyers dominated transactions over the past decade, increasing their share in recent years as Private Equity funds became increasingly selective, with high interest rates and the cost of capital putting pressure on their business model. Domestic capital prevailed throughout the period; cross-border flows proved sensitive to the exchange rate, country risk and global liquidity cycles. Geographically, the state of São Paulo concentrated most of the transactions observed, followed by industrial and services hubs in the South and Southeast.
Over the decade, different factors shaped M&A cycles in Brazil. The combination of relatively lower interest rates and strong global liquidity was decisive for the record seen in 2021, while the subsequent monetary tightening reduced risk appetite, compressing both the volume and the average size of transactions.
The exchange rate also played an important role: periods of depreciation of the real, combined with multiple compression, opened windows of opportunity for strategic buyers and long-term investors, who took advantage of more attractive valuations.
On the microeconomic and regulatory front, concession and privatization agendas and new sector frameworks — especially in energy, sanitation and healthcare — drove megadeals and fostered regional transaction hubs.
Digital transformation also consolidated itself as a cross-cutting driver of productivity and growth. Process digitalization, the adoption of artificial intelligence and the pursuit of operational efficiency came to underpin investment theses in practically every economic segment, reinforcing the leading role of technology in the M&A market.
The last decade of M&A in Brazil can be divided into eight phases, each marked by specific macroeconomic and sector conditions, with landmark transactions that illustrate its particular character.
2014–2015
Amid a sharp economic slowdown and political instability — reflected in a growing fiscal deficit and a policy interest rate (Selic) above 11% a year — the market sustained around 1,000 transactions a year. Strategic buyers took advantage of depressed valuations in consolidated sectors, especially energy, telecommunications and financial services. In April 2014, Telefónica’s acquisition of GVT for R$ 22.5 billion exemplified this opportunistic dynamic.
2016
With the beginning of the Temer administration and the prospect of fiscal and labor reforms, the environment gradually regained optimism. The Selic began a downward path and corporate credit expanded, driving consolidation in healthcare, technology and infrastructure. Itaú Unibanco’s purchase of 66% of XP Investimentos for R$ 3.6 billion spurred the search for integrated financial services platforms.
2017–2019
With interest rates falling to around 6% and anchored inflation expectations, Brazil again attracted foreign capital. Between 2017 and 2019, volume exceeded 1,200 transactions a year, led by retail, financial services and technology. The privatization of airports and highways reinforced international appetite for infrastructure assets in the period. In 2017, JBS strengthened its presence in dairy by acquiring Vigor for R$ 5.7 billion.
2020
The measures imposed by the government, on the grounds of containing the global health crisis, led to an abrupt drop in business overall, but in the second half the economy began to react after successive Selic cuts, which reached a record low of 2%, along with economic stimulus packages. Technology and healthcare transactions gained extraordinary momentum to meet the needs of the period. Magazine Luiza, for example, acquired Netshoes for R$ 115 million, accelerating its omnichannel strategy.
2021
In an environment of high global liquidity and low cost of capital, with interest rates at historically low levels, the country had its record M&A year: 2,560 deals totaling around R$ 476 billion in value. Brookfield Asset Management bought AES Tietê for R$ 5.1 billion, highlighting the flow of large investors into energy and infrastructure, sectors known to be capital-intensive.
2022
With inflation above 10% and the Selic rising to 13.75%, risk appetite cooled, which was reflected in M&A activity: 2,119 transactions and R$ 325 billion involved. Even so, large deals marked the year, such as TIM’s purchase of Oi’s mobile assets for R$ 16.5 billion, reinforcing consolidation in the telecom sector.
2023
With the Selic kept at a high level and political uncertainty due to the change of government, volume stabilized at 2,123 transactions and values fell 33%, to R$ 217 billion. Concessions and privatizations in highways and sanitation stood out in 2023. CCR completed the purchase of the BR-163/262 highway concession, expanding its infrastructure portfolio.
2024
Deal volume fell 21% (1,674 transactions), although aggregate value rose 20% (approx. R$ 260 billion), reflecting fewer but higher-value transactions. Auren acquired AES Brasil for R$ 23 billion and the São Paulo state government sold 15% of Sabesp’s capital to Equatorial for R$ 11.7 billion — transactions that illustrate the sustained focus on renewable energy and sanitation.
2025
The current moment points to a recovery path. According to PwC Brazil, 596 transactions were recorded between January and May this year, 15% more than in the same period last year, signaling a more favorable environment for M&A, despite persistent political and macroeconomic challenges such as fiscal fragility, unanchored inflation, high interest rates and exchange rate volatility. TTR Data points to a 17% increase in aggregate value in the period, reflecting the impact of large transactions in infrastructure, energy and strategic corporate consolidations.
The sector mix of transactions so far reinforces structural trends. Technology accounted for 33% of transactions, driven by digital solutions, artificial intelligence and cloud services. Consumer and Retail (15%) and Automotive (9%) also stood out, reflecting consolidation and strategic repositioning. Energy and Utilities accounted for 7.5% of the total, benefiting from infrastructure investment and the transition to renewable sources.
By investor profile, the first five months of 2025 show the predominance of strategic buyers, responsible for around 83% of transactions, against a 17% share for Private Equity funds, which accounted for approximately 20% of volume in 2024. The origin of capital confirms a mostly domestic market: 81% of transactions were carried out by Brazilian companies, while foreign investment accounted for 19%.
The outlook for 2025 is for transaction volume to keep growing, possibly exceeding 2023 figures, provided there are no significant macroeconomic shocks. Attractive valuations, the need for scale and the pursuit of innovation should continue to drive deals, especially in technology, healthcare and energy. If projections are confirmed, 2025 could establish itself as a year of recovery for M&A in Brazil, combining strategic opportunities with the need for careful risk management.
The decade leaves a more mature market, with clear sector pipelines, experienced investors and greater capital discipline. The rebound in aggregate value in 2024, despite lower volume, suggests a reopening for larger transactions in infrastructure and energy, while technology remains relevant — albeit below its 2021–2022 peak. Heading into 2025, the backdrop is one of cautious optimism: valuations remain attractive for strategic buyers, and a broader return of funds will depend on financing conditions and macro predictability.